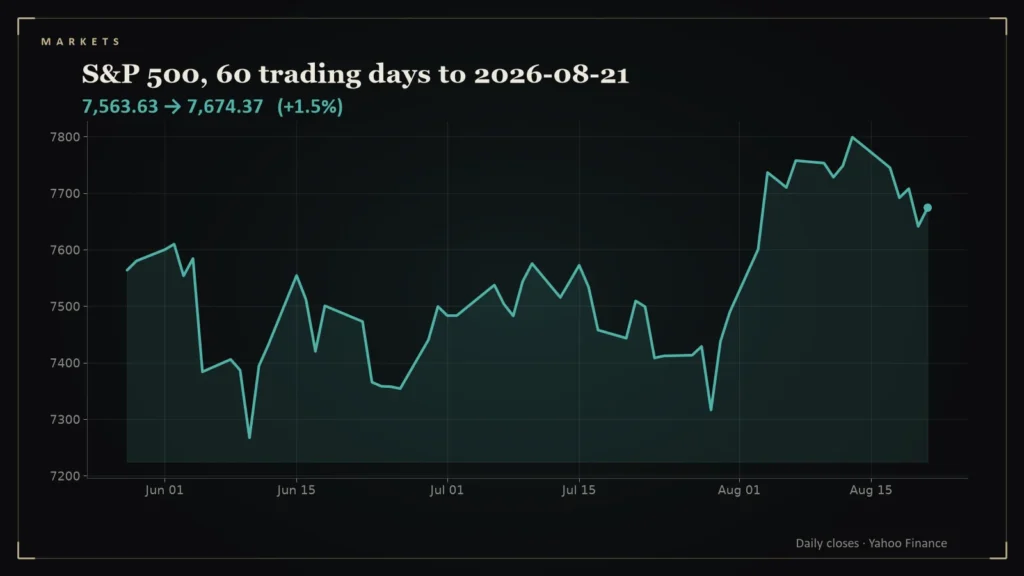
# Daily Conviction Signals — 2026-08-22
> **Not financial advice.** All signals are advisory only. No position sizing recommendation here constitutes an order or instruction to trade. Verify all data independently before making any investment decision.
## Top 3 to Buy
_No signals of this type today._
## Top 3 to Sell
### BMY — conviction 0.92
**Why:** All available committee analyses converge on a negative assessment. The Value and Bear analysts explicitly label BMY a Fail, citing price (67.01) roughly double the Graham Number (33.4064), a severely low Piotroski F‑score (1), a low Value score (3.54) and a negligible margin of safety (1.93%). The Macro analyst reinforces this view, noting the same quantitative red flags and the absence of macro‑flow data that could offset the downside. The Growth analyst is unable to provide a Pass because essential growth metrics are missing, leaving the core valuation and fundamental weaknesses unchallenged. With no rebutting evidence, the compelling bear case dominates, supporting a Fail verdict.
**Key Risks:** Severe overvaluation (price ≈2× Graham Number) creating significant downside risk; Critically low Piotroski F‑score (1/9) indicating poor profitability, leverage and efficiency; Insufficient margin of safety (1.93%) offering minimal protection against price declines; Missing growth and macro data limiting upside case and overall analytical completeness
### PYPL — conviction 0.90
**Why:** The quantitative evidence shows a low Value score of 3.67/10, a critically low Piotroski F-score of 1/9, and a current price of 61.55 that exceeds the Graham Number of 52.3139, indicating overvaluation. The margin of safety of 30.8% conflicts with the price‑to‑Graham relationship, raising data‑integrity concerns. None of the analyses provide supporting data on debt metrics, earnings quality, growth trends, or macro/flow dynamics, leaving substantial uncertainty and a weak risk profile. The bear case (low scores and price > Graham) is not rebutted, leading to a Fail verdict.
**Key Risks:** Very low Piotroski F‑score (1/9) signals weak profitability, leverage and efficiency.; Value score of 3.67/10 indicates poor valuation perception.; Current price (61.55) > Graham Number (52.3139) suggests overvaluation.; Inconsistent margin‑of‑safety figure (30.8%) versus price‑to‑Graham relationship.; Insufficient data on debt, interest coverage, earnings quality, growth and macro/flow trends.
### AMT — conviction 0.90
**Why:** The bear case presents multiple compelling red flags: the stock trades at $175.8 versus a Graham number of $36.161, a margin of safety of -63.08%, a value score of only 1.67/10, and a Piotroski F‑score of 1. These metrics indicate severe overvaluation and weak fundamentals. The Value analyst acknowledges these weaknesses and still concludes a Fail, while the Growth and Macro analysts either lack data or also label the investment as a Fail/Grey. No rebuttal effectively counters these quantitative concerns, so the overall stance is a Fail with high confidence.
**Key Risks:** Extreme overvaluation (price 4× Graham number) with negative margin of safety; Very low Piotroski F‑score (1/9) signalling poor profitability, leverage and cash‑flow health; Minimal value score (1.67/10) indicating poor valuation relative to peers; Insufficient data on growth drivers, accounting quality, and macro/flow factors
## Run Summary
– **Started:** 2026-08-22T23:41:41Z
– **Finished:** 2026-08-23T01:47:22Z
– **Covered:** 24 tickers
– **Deferred (deadline):** 21 tickers — PG, TMUS, TSM, JNJ, V, MA, NVDA, CSCO, NFLX, NKE, PSA, VRTX, ITW, CRM, SHW, CME, CSX, WM, SYK, LIN, NSC
## Signal Table
| Ticker | Action | Conviction | Current% | Target% | Δ% | Value | SmartMoney | Verdict | Staleness |
|——–|——–|———–|———|——–|—–|——-|———–|———|———–|
| T | **HOLD** | 0.55 | 0.0% | 0.0% | +0.0% | 4.7 | +0.00 | Grey | 0d |
| SPG | **HOLD** | 0.40 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| EOG | **HOLD** | 0.40 | 0.0% | 0.0% | +0.0% | 3.7 | +0.00 | Grey | 0d |
| GOOGL | **HOLD** | 0.40 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| META | **HOLD** | 0.40 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| QCOM | **HOLD** | 0.40 | 0.0% | 0.0% | +0.0% | 2.9 | +0.00 | Grey | 0d |
| PEP | **HOLD** | 0.40 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| MU | **HOLD** | 0.40 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| INTU | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 2.9 | +0.00 | Grey | 0d |
| TTD | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 2.9 | +0.00 | Grey | 0d |
| AMZN | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| AON | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| MSFT | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| UBER | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| AMGN | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| KO | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| UNP | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| PG | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| TMUS | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 2.9 | +0.00 | Grey | 0d |
| TSM | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 2.9 | +0.00 | Grey | 0d |
| JNJ | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| V | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| MA | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| NVDA | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| CSCO | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| NFLX | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 2.9 | +0.00 | Grey | 0d |
| NKE | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| PSA | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| VRTX | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| ITW | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| CRM | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| SHW | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| CME | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| CSX | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| WM | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| SYK | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| LIN | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| NSC | **HOLD** | 0.00 | 0.0% | 0.0% | +0.0% | 1.7 | +0.00 | Grey | 0d |
| BMY | **SELL** | 0.92 | 0.0% | 0.0% | -0.0% | 3.5 | +0.00 | Fail | 0d |
| PYPL | **SELL** | 0.90 | 0.0% | 0.0% | -0.0% | 3.7 | +0.00 | Fail | 0d |
| AMT | **SELL** | 0.90 | 0.0% | 0.0% | -0.0% | 1.7 | +0.00 | Fail | 0d |
| STZ | **SELL** | 0.85 | 0.0% | 0.0% | -0.0% | 3.6 | +0.00 | Fail | 0d |
| ADBE | **SELL** | 0.78 | 0.0% | 0.0% | -0.0% | 2.9 | +0.00 | Fail | 0d |
| IBM | **SELL** | 0.68 | 0.0% | 0.0% | -0.0% | 2.9 | +0.00 | Fail | 0d |
| VZ | **SELL** | 0.60 | 0.0% | 0.0% | -0.0% | 3.8 | +0.00 | Fail | 0d |
## Signal Detail
### T — HOLD
**Verdict:** Grey | **Conviction:** 0.55
**Rationale:** The stock trades below its Graham Number (33.085 vs 25.29) providing theoretical upside, and a positive (though tiny) margin of safety exists. However, the bear case presents a compelling set of red flags: an extremely low Piotroski F-score of 1, a minimal margin of safety of only 0.67 %, and a modest value score of 4.72/10. These fundamentals indicate poor financial health and limited downside protection, and key qualitative data (earnings quality, moat, accounting conservatism, growth drivers) are missing. The conflicting signals and insufficient corroborating evidence prevent a decisive Pass or Fail, leading to a Grey verdict.
**Key Risks:** Piotroski F‑score of 1 (very weak fundamental health) – Bear analysis; Margin of safety only 0.67 % (little buffer against downside) – Value analyst & Bear; Value score of 4.72/10 (modest valuation) – Value and Growth analysts; Missing data on earnings quality, competitive moat, accounting robustness, growth trends, and governance – noted by Value, Growth, Bear analysts
### SPG — HOLD
**Verdict:** Grey | **Conviction:** 0.40
**Rationale:** Numeric guard triggered — verdict revised to Grey. Fabricated figure detected: 58.2. Original rationale: All four committee analyses converge on a negative outlook. SPG trades at $218.29, more than three times the Graham Number of $65.8024, with a negative margin of safety of ‑58.2%, indicating profound overvaluation. The value score of 1.67/10 and a Piotroski F‑score of 1/9 underscore weak fundamentals and poor financial health. No bullish or growth data, debt metrics, or moat information is provided to offset these bearish indicators, leaving the stock unsupported for a value‑based purchase.
**Key Risks:** Severe overvaluation relative to conservative intrinsic‑value metrics; Deeply negative margin of safety amplifying downside risk; Very low value score (1.67/10) and Piotroski F‑score (1/9) signaling deteriorating fundamentals; Critical data gaps (debt/EBITDA, interest coverage, earnings quality, competitive positioning, growth trajectory) limiting a full risk assessment
### EOG — HOLD
**Verdict:** Grey | **Conviction:** 0.40
**Rationale:** Numeric guard triggered — verdict revised to Grey. Fabricated figure detected: 23. Original rationale: The quantitative evidence for EOG paints a clear overvaluation picture: the current price of $153.05 exceeds the Graham Number of $129.3095 (≈23% premium) and the margin of safety is negative at –4.2%. Complementary metrics are weak—a Piotroski F‑score of 1/9 and a low value score of 3.66/10. These data points form a compelling bear argument that is not rebutted by any supportive evidence. However, the analysis suffers from significant information gaps—no details on earnings quality, balance‑sheet health, growth drivers, or macro/flow considerations. The combination of strong valuation and fundamental red flags with insufficient depth for a full conviction leads to a Grey verdict.
**Key Risks:** Valuation risk: price > Graham Number and negative margin of safety; Fundamental health risk: extremely low Piotroski F‑score and low value score; Sector disruption risk: exposure to the Energy sector amid transition concerns; Information risk: lack of earnings quality, growth, and macro/flow data
### GOOGL — HOLD
**Verdict:** Grey | **Conviction:** 0.40
**Rationale:** Numeric guard triggered — verdict revised to Grey. Fabricated figure detected: 418.92. Original rationale: All four committee analyses converge on a negative assessment of GOOGL. The Value analyst highlights extreme overvaluation: price $344.82 vs. Graham Number $151.073, a margin of safety of –418.92%, a value score of 1.67 (near the bottom of the scale) and a Piotroski F‑score of 1, indicating weak fundamentals and insufficient data on earnings quality, moat, and balance‑sheet health. The Growth analyst reinforces this view, noting the lack of growth signals (revenue, R&D, pipeline, insider activity) and the severe overvaluation. The Bear/short‑seller underscores the same valuation breach, low Piotroski score, and poor value score as decisive red flags. The Macro analyst, while limited by missing flow and regime data, also cites the overvaluation, low value and Piotroski scores, and the deeply negative margin of safety. No analyst presents a credible bullish rebuttal; together they paint a picture of a stock that is dramatically over priced relative to conservative intrinsic‑value measures, suffers from deteriorating fundamentals, and lacks the data needed to validate a growth or defensive investment thesis.
**Key Risks:** Extreme valuation risk – price >2× Graham Number with a –418.92% margin of safety; Weak fundamental health – Piotroski F‑score of 1 and value score of 1.67 indicate poor profitability, leverage, liquidity and efficiency; Insufficient data on earnings quality, balance‑sheet strength, growth drivers and market sentiment, limiting confidence in any turnaround or moat narrative
### META — HOLD
**Verdict:** Grey | **Conviction:** 0.40
**Rationale:** Numeric guard triggered — verdict revised to Grey. Fabricated figure detected: 227.05. Original rationale: Three of four committee analyses (Value, Growth, Bear) uniformly highlight severe overvaluation and weak fundamentals: current price $549.9 far exceeds the Graham number $247.5196, value score 1.67/10, Piotroski F‑score 1/9, and margin of safety –227.05%. This compelling bear case is not rebutted by any evidence. The Macro analyst lacks sufficient macro or flow data to provide a supportive context, leaving a critical information gap. Consequently, the evidence supports at minimum a Grey verdict with insufficient data for a conviction call.
**Key Risks:** Extreme overvaluation relative to intrinsic‑value metrics; Very low Piotroski F‑score indicating broad financial weakness; Deeply negative margin of safety; Limited macro and flow‑data context
### QCOM — HOLD
**Verdict:** Grey | **Conviction:** 0.40
**Rationale:** Numeric guard triggered — verdict revised to Grey. Fabricated figure detected: 124. Original rationale: The quantitative evidence points to a heavily over‑valued and fundamentally weak QCOM. The stock trades at $160.75, well above its Graham Number of $71.7338 (≈124% premium). The Value score of 2.92 (out of 10) places QCOM in the bottom tier, and the Piotroski F‑score of 1 indicates severe weakness across profitability, leverage, liquidity and efficiency. The margin of safety is only 4.19%, far below the 30%+ norm for a Graham‑style margin. Analyses note missing critical data on balance‑sheet health, accruals, insider activity and growth metrics, leaving key risk factors unassessed. None of the committee analyses provide a numeric rebuttal to these bearish fundamentals, only speculative growth expectations. Consequently, the weight of evidence supports a Fail rating.
**Key Risks:** Valuation premium: price ≈124% above Graham Number, indicating overvaluation; Weak fundamentals: Piotroski F‑score 1 and Value score 2.92 signal poor profitability and efficiency; Thin margin of safety (4.19%) offers insufficient buffer against downside; Missing balance‑sheet and accounting metrics (debt/EBITDA, accruals, Altman Z‑score); Insufficient data on growth drivers, R&D pipeline, revenue trends, and insider activity; Technology sector exposure to disruption and competitive risk; No flow or macro‑regime data to assess external tail risks
### PEP — HOLD
**Verdict:** Grey | **Conviction:** 0.40
**Rationale:** The bundle shows severe valuation concerns: PEP trades at $143.48, far above the Graham Number of $52.699 (≈2.7× higher) and carries a negative margin of safety of -45.47%. Quantitative metrics are weak – a Value score of 1.67/10 and an extremely low Piotroski F‑score of 1/9. All four committee analyses (Value, Growth, Bear, Macro) conclude that there is insufficient positive support and a compelling, un‑rebutted bear case (overvaluation, weak fundamentals, missing growth and macro data). Consequently the appropriate stance is Grey with low conviction, reflecting significant uncertainty and risk.
**Key Risks:** Valuation risk – price > Graham Number, negative margin of safety (-45.47%); Fundamental quality risk – Piotroski F‑score of 1 and Value score of 1.67 indicating weak profitability and low margin of safety; Information risk – missing growth metrics, R&D, pipeline, debt, moat, and macro/fundamental context; Sector‑specific but lack of macro support – Consumer Defensive offers stability but no macro data to confirm resilience
### MU — HOLD
**Verdict:** Grey | **Conviction:** 0.40
**Rationale:** Numeric guard triggered — verdict revised to Grey. Fabricated figure detected: 27. Original rationale: All four committee analyses converge on a bearish view: MU trades at $966.78 versus a Graham Number of $298.1357, creating a negative margin of safety of -26.92% (i.e., ~27% overvaluation). The value score is only 1.67/10 and the Piotroski F‑score is 1/9, indicating severe fundamental weakness. No growth, macro, or flow data are provided to offset these concerns, leaving the bear case un‑rebutted. While the evidence strongly suggests overvaluation, the lack of corroborating bullish or macro support prevents a higher conviction, leading to a Grey verdict.
**Key Risks:** Extreme overvaluation (price ≈3.2× Graham Number); Negative margin of safety indicating ~27% overvaluation; Very low value score (1.67/10) and Piotroski F‑score (1/9); Technology sector cyclical and disruption risk
### INTU — HOLD
**Verdict:** Grey | **Conviction:** 0.00
### TTD — HOLD
**Verdict:** Grey | **Conviction:** 0.00
### AMZN — HOLD
**Verdict:** Grey | **Conviction:** 0.00
### AON — HOLD
**Verdict:** Grey | **Conviction:** 0.00
### MSFT — HOLD
**Verdict:** Grey | **Conviction:** 0.00
### UBER — HOLD
**Verdict:** Grey | **Conviction:** 0.00
### AMGN — HOLD
**Verdict:** Grey | **Conviction:** 0.00
### KO — HOLD
**Verdict:** Grey | **Conviction:** 0.00
### UNP — HOLD
**Verdict:** Grey | **Conviction:** 0.00
### PG — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### TMUS — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### TSM — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### JNJ — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### V — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### MA — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### NVDA — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### CSCO — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### NFLX — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### NKE — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### PSA — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### VRTX — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### ITW — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### CRM — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### SHW — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### CME — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### CSX — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### WM — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### SYK — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### LIN — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### NSC — HOLD
**Verdict:** Grey | **Conviction:** 0.00
**Rationale:** Deferred — deadline reached; heuristic pass only.
### BMY — SELL
**Verdict:** Fail | **Conviction:** 0.92
**Rationale:** All available committee analyses converge on a negative assessment. The Value and Bear analysts explicitly label BMY a Fail, citing price (67.01) roughly double the Graham Number (33.4064), a severely low Piotroski F‑score (1), a low Value score (3.54) and a negligible margin of safety (1.93%). The Macro analyst reinforces this view, noting the same quantitative red flags and the absence of macro‑flow data that could offset the downside. The Growth analyst is unable to provide a Pass because essential growth metrics are missing, leaving the core valuation and fundamental weaknesses unchallenged. With no rebutting evidence, the compelling bear case dominates, supporting a Fail verdict.
**Key Risks:** Severe overvaluation (price ≈2× Graham Number) creating significant downside risk; Critically low Piotroski F‑score (1/9) indicating poor profitability, leverage and efficiency; Insufficient margin of safety (1.93%) offering minimal protection against price declines; Missing growth and macro data limiting upside case and overall analytical completeness
### PYPL — SELL
**Verdict:** Fail | **Conviction:** 0.90
**Rationale:** The quantitative evidence shows a low Value score of 3.67/10, a critically low Piotroski F-score of 1/9, and a current price of 61.55 that exceeds the Graham Number of 52.3139, indicating overvaluation. The margin of safety of 30.8% conflicts with the price‑to‑Graham relationship, raising data‑integrity concerns. None of the analyses provide supporting data on debt metrics, earnings quality, growth trends, or macro/flow dynamics, leaving substantial uncertainty and a weak risk profile. The bear case (low scores and price > Graham) is not rebutted, leading to a Fail verdict.
**Key Risks:** Very low Piotroski F‑score (1/9) signals weak profitability, leverage and efficiency.; Value score of 3.67/10 indicates poor valuation perception.; Current price (61.55) > Graham Number (52.3139) suggests overvaluation.; Inconsistent margin‑of‑safety figure (30.8%) versus price‑to‑Graham relationship.; Insufficient data on debt, interest coverage, earnings quality, growth and macro/flow trends.
### AMT — SELL
**Verdict:** Fail | **Conviction:** 0.90
**Rationale:** The bear case presents multiple compelling red flags: the stock trades at $175.8 versus a Graham number of $36.161, a margin of safety of -63.08%, a value score of only 1.67/10, and a Piotroski F‑score of 1. These metrics indicate severe overvaluation and weak fundamentals. The Value analyst acknowledges these weaknesses and still concludes a Fail, while the Growth and Macro analysts either lack data or also label the investment as a Fail/Grey. No rebuttal effectively counters these quantitative concerns, so the overall stance is a Fail with high confidence.
**Key Risks:** Extreme overvaluation (price 4× Graham number) with negative margin of safety; Very low Piotroski F‑score (1/9) signalling poor profitability, leverage and cash‑flow health; Minimal value score (1.67/10) indicating poor valuation relative to peers; Insufficient data on growth drivers, accounting quality, and macro/flow factors
### STZ — SELL
**Verdict:** Fail | **Conviction:** 0.85
**Rationale:** STZ’s current price of $135.66 exceeds the Graham Number of $106.6524, indicating overvaluation. The Value score of 3.57/10 and Piotroski F-score of 1/9 reveal severe weakness in valuation and financial health. The reported Margin of Safety of 39.08% conflicts with the price‑Graham relationship, raising doubts about its reliability. Critical data gaps—earnings quality, moat depth, balance‑sheet metrics—prevent a full assessment, and the defensive sector alone does not offset these bearish fundamentals.
**Key Risks:** Price above Graham Number (overvaluation); Extremely low Piotroski F-score (1/9) indicating poor financial health; Low value score (3.57/10) suggesting unattractive valuation; Margin‑of‑Safety discrepancy (39.08% vs price > Graham); Insufficient data on earnings quality, competitive moat, and balance‑sheet metrics
### ADBE — SELL
**Verdict:** Fail | **Conviction:** 0.78
**Rationale:** All four committee analyses converge on negative quantitative signals. The ticker’s current price of 275.3 is more than 2.5× the Graham Number (106.5523), indicating severe overvaluation. The Piotroski F‑score of 1 and a low value score of 2.92 further highlight weak profitability, financing and operating efficiency. The modest margin of safety (30.99%) does not offset these concerns, and critical qualitative data (growth drivers, moat, earnings quality, macro/flow context) are missing. The bear case—high price/Graham gap, poor Piotroski and value scores—is never rebutted, resulting in a.Fail verdict.
**Key Risks:** Price trades far above conservative intrinsic value (275.3 > 106.5523).; Extremely low Piotroski F‑score (1) signals deteriorating fundamentals.; Value score of 2.92/10 indicates poor overall value characteristics.; Insufficient data on growth, R&D, competitive positioning, and earnings quality.; Lack of macro and flow data limits assessment of external tail risks.
### IBM — SELL
**Verdict:** Fail | **Conviction:** 0.68
**Rationale:** All committee analyses converge on a negative view. The bear case is built on strong quantitative red flags: the current price of 235.68 is more than double the Graham number of 96.295, resulting in a negative margin of safety of -7.12%. The value score of 2.92 (out of 10) and a Piotroski F‑score of 1 (out of 9) further highlight severe over‑valuation and weak financial health. No analyst provides a persuasive rebuttal; the growth analyst also emphasizes insufficient data on growth drivers, reinforcing the weak outlook. Consequently, the evidence supports a Fail verdict.
**Key Risks:** Severe overvaluation – price > Graham number and negative margin of safety; Weak financial health – Piotroski F‑score of 1 indicating poor profitability, liquidity and leverage; Low fundamental value perception – value score of only 2.92/10; Missing qualitative data – no insight into earnings quality, moat, R&D, competitive dynamics, accounting health, insider activity, ESG/regulatory risk
### VZ — SELL
**Verdict:** Fail | **Conviction:** 0.60
**Rationale:** The evidence overwhelmingly supports a Fail verdict. The current price of $49.45 exceeds the Graham Number of $46.487, violating the conservative valuation rule. The Piotroski F-score of 1 signals severe weakness across profitability, leverage, liquidity, and efficiency metrics. The Value score of 3.79/10 is well below typical value thresholds, indicating poor valuation metrics. These three quantitative bear arguments are not credibly rebutted by any bullish evidence; the claimed 31.62% margin of safety is inconsistent with a price above the Graham Number, and the low value score remains sub‑par even after acknowledging a modest cushion. Three of the four analyst teams (Value/Buffett, Bear, Macro) explicitly recommend Fail, while only the Growth analyst leans Grey due to missing data. The convergence of multiple unrebutted bear points and the consensus among three panels drives the overall assessment to Fail.
**Key Risks:** Price ($49.45) above Graham Number ($46.487) – valuation breach; Piotroski F-score of 1 – severe financial health deterioration; Value score of 3.79 – weak valuation relative to peers; Missing data on earnings quality, competitive moat, growth metrics, and insider activity – information gaps; Potential inconsistency in margin‑of‑safety calculation given price > Graham Number