Laws create markets by creating obligations. The GENIUS Act, which regulates stablecoins, is a good example, because one of its requirements has a quiet, valuable side effect for insurers.
- The GENIUS Act, the stablecoin law, requires issuers to hold reserves with qualified custodians, creating demand for custody insurance [1].
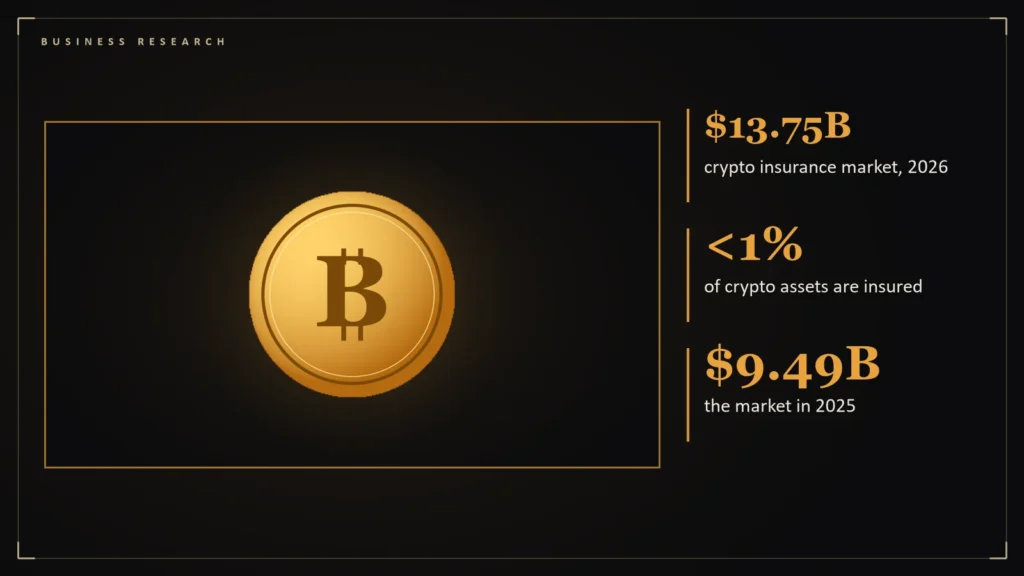
- The global crypto insurance market was $9.49 billion in 2025 and is projected at $13.75 billion in 2026 (Grand View Research, as cited) [1].
- Fewer than 1 percent of crypto assets are insured, leaving over $1 trillion uninsured [1].
- The GENIUS Act was signed into law, while the CLARITY Act, covering market structure, remains stalled in the Senate [2].
The requirement
The GENIUS Act requires stablecoin issuers to hold their reserves with qualified custodians [1]. Once the law says where the money has to sit, the next question is who insures it if the custodian fails or is hacked. That turns custody insurance from a nice-to-have into something regulators and institutional clients ask for.
The market today
The global crypto insurance market reached $9.49 billion in 2025 and is projected to reach $13.75 billion in 2026, according to Grand View Research data cited by Spark. Yet less than 1 percent of crypto assets are insured, leaving over $1 trillion uncovered, and about 89 percent of holders are uninsured [1].
Where the capacity comes from
Most coverage runs through Lloyd’s of London syndicates, including Arch, Atrium, Beazley and Canopius. Marsh has assembled the largest facility, with $825 million of capacity, and the crypto-native agent Evertas offers per-policy limits of up to $420 million. Premiums typically run from 0.5 to 5 percent a year, far above the 0.1 to 0.5 percent for fine art or precious metals, reflecting the risk and thin underwriting capacity [1].
What policies do not cover
- Market volatility and regulatory action.
- Smart contract bugs and user error.
- Blockchain-level failures and, generally, self-custody losses [1].
What policies cover, and what they do not
The coverage list shows where the market is mature. Policies typically cover external theft and cyberattacks, internal fraud and employee misconduct, physical destruction of signing devices or cold storage, key loss by the custodian and social engineering [1]. They typically exclude market volatility and price declines after a theft, regulatory freezes or seizures, smart-contract vulnerabilities, user error such as wrong addresses or personal key loss, blockchain-level failures and traditional self-custody losses [1]. Some capacity is substantial: Evertas offers up to $420 million per policy, having nearly tripled its limits in 2026, BitGo has $250 million backed through a Lloyd’s syndicate and AnchorWatch offers $100 million per customer for insured self-custody Bitcoin [1].
The scale of losses explains the premiums. Crypto theft totaled $6.75 billion in 2025, with an average loss of about $33.75 million per incident, and the February 2025 Bybit hack alone took about $1.5 billion from Ethereum, roughly 69 percent of everything stolen from crypto services that year [1]. About 89 percent of crypto holders remain uninsured [1]. The decentralized cover provider Nexus Mutual has protected more than $6 billion since 2019 and generated $5.7 million in cover fees in 2025 [1]. A market this small relative to the assets it protects is why the law’s custody rules matter for its growth.
The wider legislative picture
The GENIUS Act is the one that passed. Its companion, the CLARITY Act on market structure, has cleared the House and the Senate Banking Committee but, as of late September 2026, had not reached a final Senate vote [2]. Until it does, custodians and insurers operate with rules for stablecoins and uncertainty for everything else. This is analysis, not investment advice.
Questions readers ask
What does the GENIUS Act require?
Among other things, that stablecoin issuers hold reserves with qualified custodians, which drives demand for custody insurance [1].
How big is the crypto insurance market?
$9.49 billion in 2025 and a projected $13.75 billion in 2026, though less than 1 percent of crypto assets are insured [1].
References
- Crypto Custody Insurance: How the Market Is Evolving to Cover Digital Asset Risk — Spark — https://www.spark.money/research/crypto-custody-insurance-market-growth
- The CLARITY Act in 2026: Where US Crypto Market Structure Actually Stands — Tech Insider — https://tech-insider.org/clarity-act-2026-status/