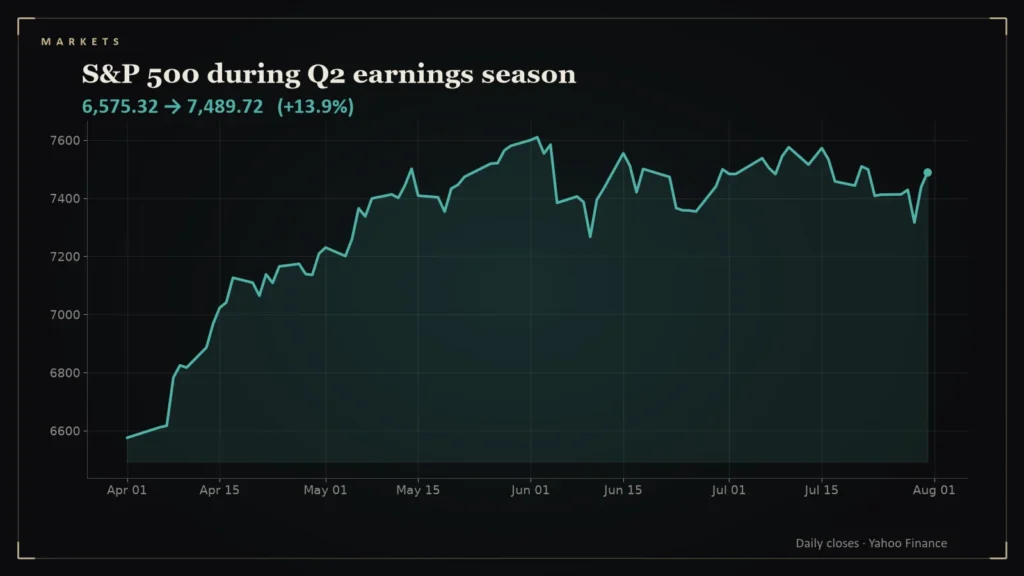
Strong earnings season, but from whom? The answer changes as more reports come in, and it explains a lot about this year’s market.
- As of August 7, ten of the eleven S&P 500 sectors reported year-over-year earnings growth, led by Energy, Communication Services and Consumer Discretionary [1].
- Earlier, on July 24, Energy, Communication Services, Information Technology and Materials led, and Health Care was the sole decliner [2].
- Blended earnings growth was 50.4 percent as of August 7, 32.0 percent excluding Alphabet and Amazon [1].
- Analysts expected Q3 and Q4 growth of 27.4 and 25.2 percent [1].
The early leaders
FactSet’s July 24 update, with 27 percent of the S&P 500 reported, had Energy, Communication Services, Information Technology and Materials leading with double-digit growth, and Health Care the only sector with declining earnings [2]. At that stage blended growth was 37.9 percent, or 25.9 percent excluding Alphabet [2].
The fuller picture
By August 7, with 88 percent reported, ten of eleven sectors showed year-over-year growth, and the top three were Energy, Communication Services and Consumer Discretionary. Blended earnings growth had climbed to 50.4 percent, or 32.0 percent excluding two companies, Alphabet and Amazon [1].
Why those sectors
- Energy: oil above $100 for much of the year lifts producers’ profits directly [3].
- Communication Services: includes Alphabet, whose results were boosted by a $98 billion gain [2].
- Consumer Discretionary: includes Amazon, whose profit was lifted by investment gains [1].
Two of the three leading sectors contain the two companies FactSet flags as outliers, which is why the sector table has to be read alongside the footnote on investment gains.
Beyond the three leaders
FactSet’s August 7 update gives more of the picture. Eight of the ten growing sectors posted double-digit earnings growth, with Energy, Communication Services, Consumer Discretionary, Information Technology and Materials named as leaders and Health Care the only sector reporting a year-over-year decline [1]. Revenue tells a similar story: blended revenue growth was 15.0 percent, 76 percent of companies beat revenue estimates and the collective revenue surprise was 3.2 percent. Five of the eleven sectors reported double-digit revenue growth, led by Energy, Information Technology and Communication Services [1].
Valuation did not run away from history. The forward 12-month price-to-earnings ratio was 20.0, slightly above the five-year average of 19.9 and the ten-year average of 19.0 [1]. Analysts projected earnings growth of 27.4 percent for the third quarter, 25.2 percent for the fourth and 30.0 percent for calendar 2026 [1]. The report also attributes much of the increase in earnings growth since quarter-end to Alphabet and Amazon, whose gains in other income from equity holdings and investments lifted the blended figure [1].
Looking forward
Analysts projected earnings growth of 27.4 percent in the third quarter, 25.2 percent in the fourth, and 30.0 percent for the full year [1]. Those are forecasts, and in an energy-driven year they depend on oil staying high and consumers continuing to spend. This is analysis, not investment advice.
Questions readers ask
Which sectors led Q2 2026 earnings growth?
As of August 7: Energy, Communication Services and Consumer Discretionary, with ten of eleven sectors growing [1].
Was any sector down?
On July 24, Health Care was the only sector with declining earnings [2].
References
- S&P 500 Earnings Season Update, August 7, 2026 — FactSet — https://insight.factset.com/sp-500-earnings-season-update-august-7-2026
- S&P 500 Earnings Season Update, July 24, 2026 — FactSet — https://insight.factset.com/sp-500-earnings-season-update-july-24-2026
- Brent Crude Oil (BZ=F) Historical Prices — Yahoo Finance — https://finance.yahoo.com/quote/BZ%3DF/history/